Travelers beats profit forecasts by wide margin as record investment income offsets storm losses
The Dow component posted third-quarter core earnings of $9.18 a share, far above Wall Street estimates, as record investment income and favorable reserve trends outweighed higher storm losses and a $295 million charge tied to decades-old asbestos claims.
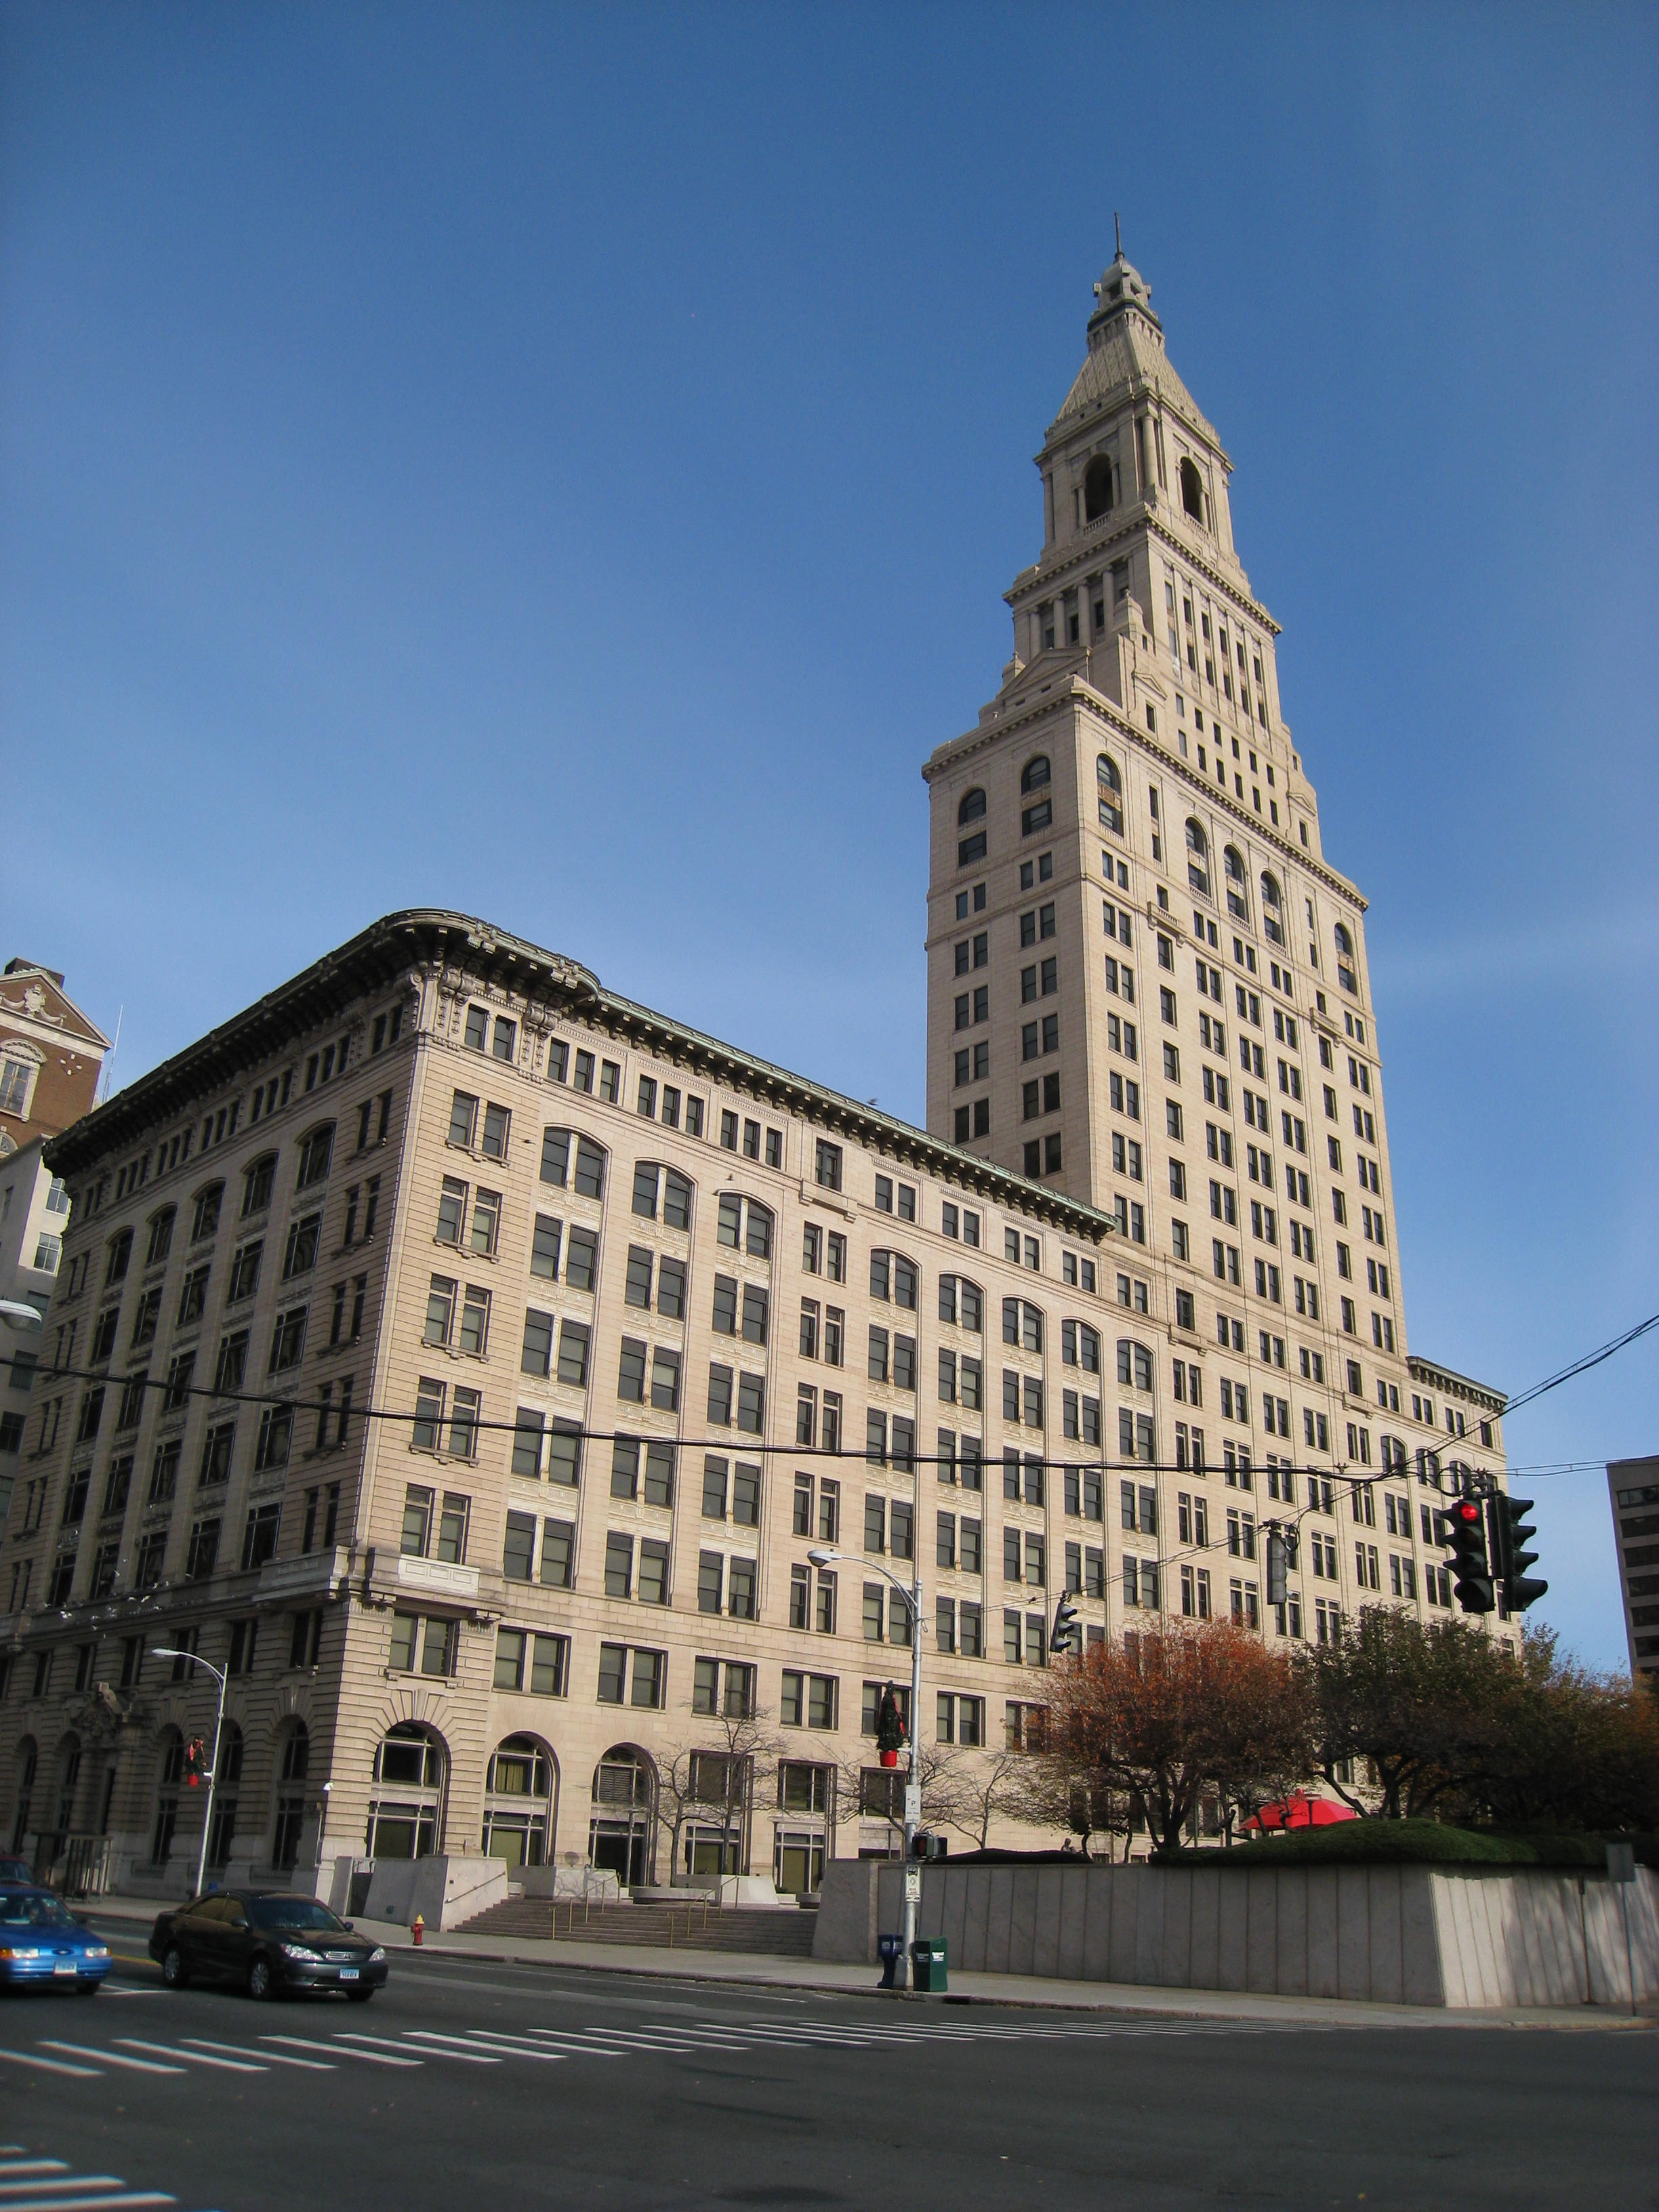
The Travelers Companies, the property-and-casualty insurer and Dow Jones Industrial Average component, reported third-quarter 2026 results on Friday that beat Wall Street's profit and revenue estimates by a wide margin, even as catastrophe losses from storms rose sharply and the company absorbed a fresh charge tied to legacy asbestos liabilities.
Net income for the quarter came to $1.917 billion, or $9.04 per diluted share, up from $1.888 billion, or $8.24 per share, a year earlier, according to the company's third-quarter earnings release filed with the Securities and Exchange Commission. On a core basis, which strips out realized investment gains and losses, earnings were $1.947 billion, or $9.18 per diluted share. Several analyst consensus estimates compiled by data providers before the release had clustered between roughly $7.25 and $7.49 per share, meaning the company topped expectations by close to $2 a share, or more than 20 percent.
The numbers
Total revenue was $12.41 billion, roughly flat from $12.47 billion a year earlier but still ahead of most analyst forecasts, which had centered closer to $11.3 billion to $12.4 billion. The consolidated combined ratio, a core measure of underwriting profitability in which a lower number is better, improved to 86.8 percent from 87.3 percent a year earlier. The underlying combined ratio, which excludes catastrophe losses and prior-year reserve changes, came in at 84.1 percent.
Net investment income, Travelers said, set a record at $1.098 billion pre-tax, up 6 percent from a year earlier, driven by higher yields on its fixed-income portfolio. That single line item was the main driver of the earnings beat. Catastrophe losses, by contrast, rose to $538 million pre-tax from $402 million a year earlier, an increase of roughly 34 percent that the company attributed mainly to severe wind, tornado and hail storms across multiple states in the central United States. Net written premiums were $11.48 billion, essentially flat, though the company said premiums rose about 2 percent when excluding the effect of its earlier divestiture of its Canadian personal-insurance operations, according to the quarterly report filed with the SEC.
Context: an old liability resurfaces
Travelers also disclosed that its annual actuarial review of legacy asbestos exposure, tied to policies written decades ago, resulted in a $295 million addition to reserves in the Business Insurance segment during the quarter, up from a $277 million addition in the same review a year earlier. Asbestos liabilities remain a recurring, if shrinking, drag on large, long-established insurers that wrote general liability and workers' compensation coverage before the health risks of the mineral were fully understood; Travelers' net asbestos reserves stood at roughly $1.22 billion as of mid-2026. That charge was folded into the company's broader prior-year reserve review, which produced $234 million of net favorable development across all three of its business segments for the quarter, according to the company's statistical supplement filed alongside the earnings release — meaning favorable trends elsewhere in the reserve book more than offset the asbestos charge.
Who is affected: a shrinking personal book, a growing commercial one
The results underscored a continuing split inside Travelers' business. Business Insurance, the company's largest segment, posted segment income of $1.036 billion, up from $907 million a year earlier, with net written premiums of $5.868 billion, up about 4 percent excluding divestiture effects, and a combined ratio that improved to 90.9 percent from 92.9 percent. The smaller Bond & Specialty Insurance segment grew net written premiums by about 12 percent. Personal Insurance, which covers auto and home policies for individual customers, saw net written premiums fall 7 percent, or 3 percent excluding the Canadian divestiture, as the company has continued to prioritize pricing and profitability over policy count; personal auto policies in force fell roughly 9 percent year over year and homeowners policies in force fell nearly 7 percent. The pattern reflects a broader, multiyear retreat by large personal-lines insurers from unprofitable auto and home business written during a period of elevated claims costs, even as commercial underwriting has stayed comparatively strong.
Reaction
Travelers shares fell as much as 4.4 percent in premarket trading on Friday despite the earnings beat, as some investors focused on the jump in catastrophe losses and on the shrinking personal-lines policy counts rather than the headline profit figure — a reminder that a company which has topped analyst estimates in each of its last several reported quarters can still disappoint a market that had priced in an even larger surprise. Travelers Chairman and Chief Executive Alan Schnitzer struck a confident tone on the matter in prepared remarks accompanying the release.
"We're pleased to report excellent third quarter results. Profitability was excellent on both a reported and underlying basis." — Alan Schnitzer, Chairman and Chief Executive Officer, The Travelers Companies
Chief Financial Officer Dan Frey, discussing the results with analysts, said catastrophe losses in the quarter were "$538 million pre-tax, consisting mainly of tornado hail events in the central U.S.," and that the annual asbestos review in the Business Insurance segment "resulted in a charge of $295 million." Travelers also returned capital to shareholders during the quarter, repurchasing 4 million shares for $1.5 billion under its board authorization and declaring $261 million in common-stock dividends.
What happens next
Travelers' results arrived in a week dominated by bank earnings, but as one of the first major insurers to report for the period, its numbers will be watched closely by analysts assessing how the broader property-casualty sector absorbed an active season of U.S. severe-weather and hail activity. Rival insurers with large commercial and personal-lines books are due to report results over the coming weeks, which should show whether the storm losses and underwriting discipline reflected in Travelers' numbers were industrywide or company-specific. Travelers' management and additional earnings materials, including a recorded conference-call replay, are available on the company's investor relations site. Investors will next look to the company's fourth-quarter report, typically released in late January, for an update on pricing trends in personal auto and home insurance and on whether catastrophe losses moderate heading into 2027.

Conduent agrees to pay $80 million to settle data breach that exposed 62 million people's records

Strategy asks shareholders to approve daily dividends on its discounted bitcoin preferred stock

Proofpoint to acquire Varonis Systems in $6.3 billion cybersecurity deal
